$60K Income, Buying a $1.6M-Plus Property and Being Pushed Toward a B Lender? A Family Guarantor and Rental Income Secured a $1M-Plus Bank Mortgage at About 3.4%
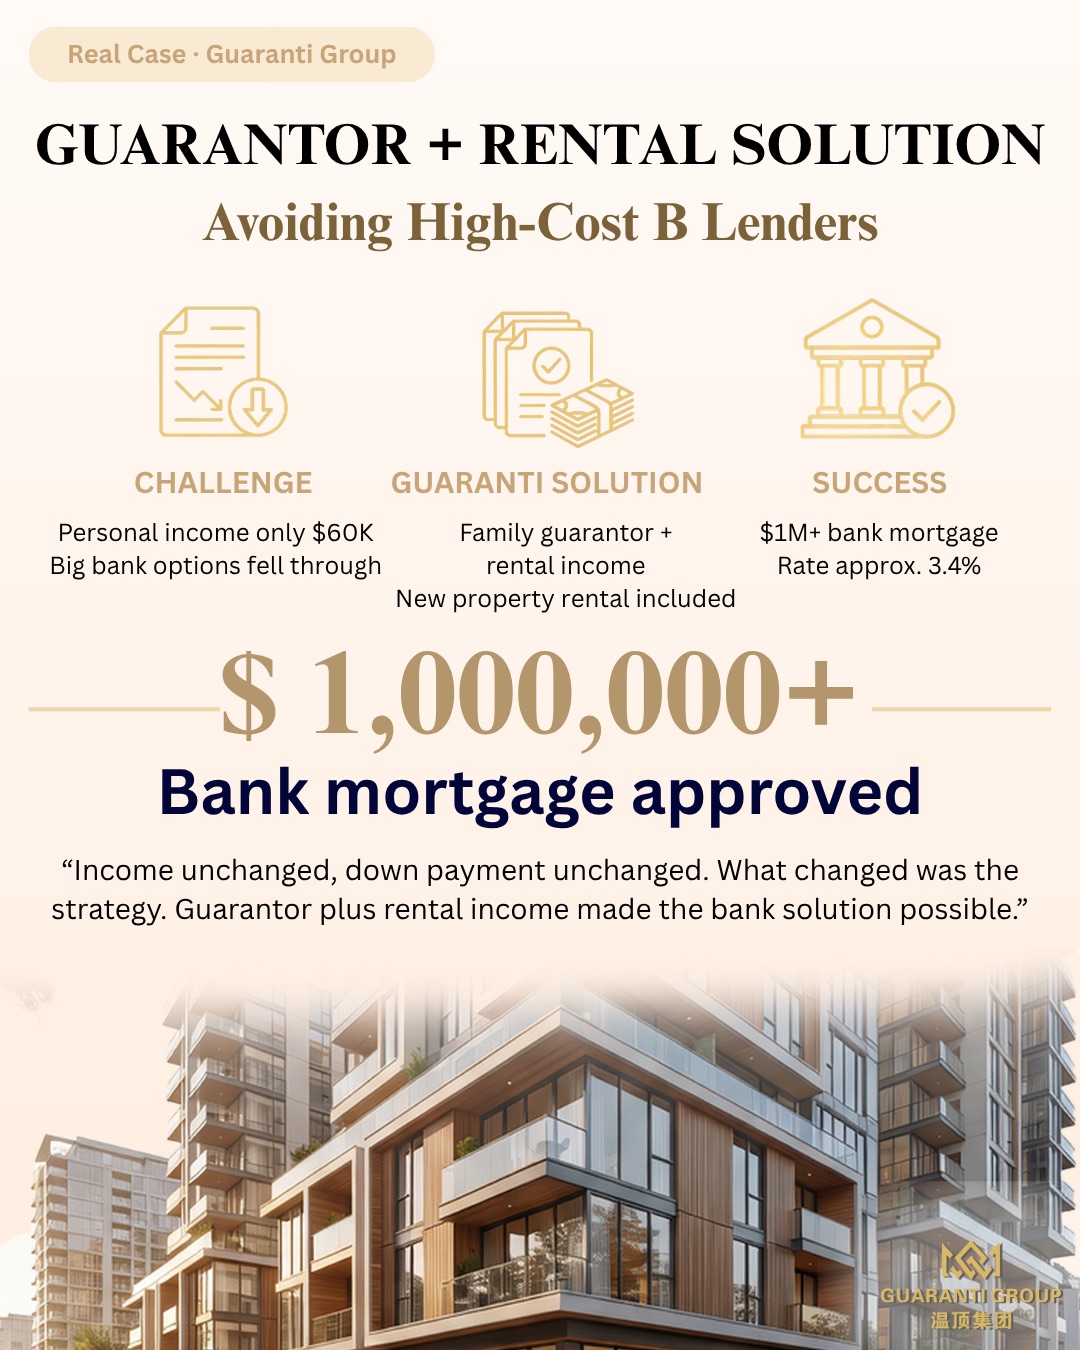
The client had personal annual income of approximately $60,000 and needed financing for a new property intended for rental use. Because the mortgage requirement was substantial, the original major-bank route did not pass when assessed on the client’s income alone.
The challenge involved more than the requested loan amount. A bank considers the applicant’s income, down payment, liabilities, intended use of the property and whether rental income can be included under its policy. Based only on employment income, the debt-service picture could not support financing of more than $1 million.
After the client approached Guaranti Group, we reviewed the application as a complete financial picture. The client’s income and down payment did not change, but a family member could join as guarantor. The new property also had a genuine rental plan, creating an opportunity for eligible rental income to be considered.
The Guaranti team compared how different banks assessed guarantors, rental properties and rental income. We then reorganized the application around a compliant guarantor structure and the supporting rental documentation. The goal was not to change the client’s underlying circumstances, but to present all relevant facts clearly and match them with a bank policy suited to this combination.
The client ultimately obtained a bank mortgage of more than $1 million at an approved rate of approximately 3.4%, avoiding a higher-cost B-lender solution.
This case highlights an important point: when personal income alone cannot support the target mortgage, the only answers are not necessarily reducing the budget or moving to a higher-cost lender. Whether a guarantor can participate, how rental income is calculated and how each bank views the same facts can materially change the outcome.
The income did not change. The down payment did not change. What changed was the financing strategy. Combining a guarantor with rental income made a bank solution possible.
When one bank path does not fit, Guaranti helps clients explore other suitable possibilities.
The rates, amounts and timelines in this story were that client’s actual circumstances at the time. Lending conditions change and every application is assessed on its own merits — these figures are not an indication of what any other applicant will obtain, and are not a promise of any kind.
Cases are anonymized and drawn from real client situations.