Court Approved the Foreclosure Purchase — Then the Bank Declined Before Closing. A $400K-Plus Private Loan Was Arranged in Two Days
The client had been renting while steadily saving a down payment and planning to buy a home of his own. When his landlord decided to sell the property where he was living, he accelerated that plan.
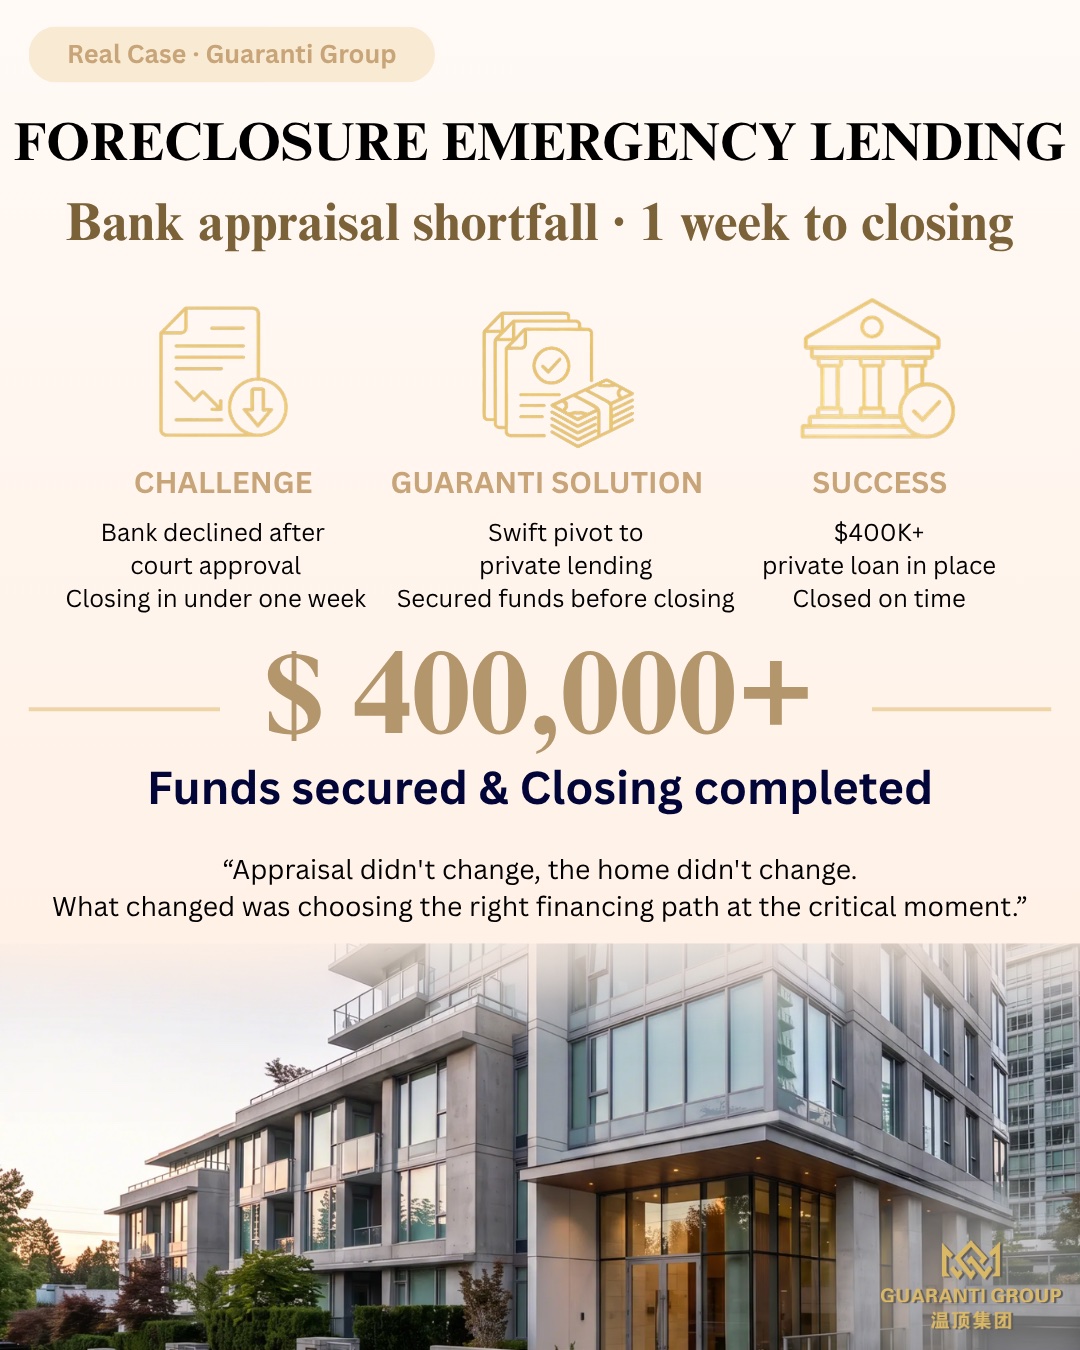
He eventually found a foreclosure property that suited him. After submitting an offer and attending the court hearing, the offer received court approval. It seemed that the biggest hurdle was over and that only financing and closing remained. The problem arose at the final stage.
After the bank ordered an appraisal, the appraiser concluded that the property value did not support the purchase price and requested financing. The bank could no longer proceed with the mortgage as planned.
By then, closing was less than a week away. The offer had already been approved by the court and the completion date was approaching. Without financing in place, the transaction—and the deposit already paid—could face further risk.
The client contacted Guaranti Group.
We immediately reviewed the down payment, income and overall financial position, along with the property details, court-approval documents and the reason the original bank could not proceed.
The key issue was not that the client had no financing options. It was that there was no longer enough time for a conventional bank application, a new appraisal, underwriting and funding before completion.
Instead of repeatedly trying the same bank route, we adjusted the financing strategy around the client’s most urgent need: securing the funds required to close through a private lender.
The Guaranti team matched the client with a suitable private-lending option and moved the file forward on all fronts. From the time the client contacted us, more than $400,000 in private financing was arranged within two days.
The client completed the purchase on schedule, preventing a financing problem from interrupting a transaction that had already reached its final stage.
This private loan was not intended to be the client’s permanent financing arrangement. It solved one clearly defined problem: time.
Once the title transfer was complete and the immediate deadline had passed, there would be more time to reassess the client’s circumstances and arrange a transition to conventional bank financing better suited to long-term ownership.
The property did not change, and neither did the bank’s appraisal. What changed was the decision about which problem needed to be solved first at that point in the transaction.
Private lending is not always the long-term destination. When deadlines are urgent and a conventional bank process can no longer be completed in time, it can provide a bridge that allows a transaction to close.
First solve whether the purchase can close on time. Then solve which long-term financing structure is more suitable.
When one bank path does not fit, Guaranti helps clients explore other suitable possibilities.
The rates, amounts and timelines in this story were that client’s actual circumstances at the time. Lending conditions change and every application is assessed on its own merits — these figures are not an indication of what any other applicant will obtain, and are not a promise of any kind.
Cases are anonymized and drawn from real client situations.